
How we investBuilding net worth
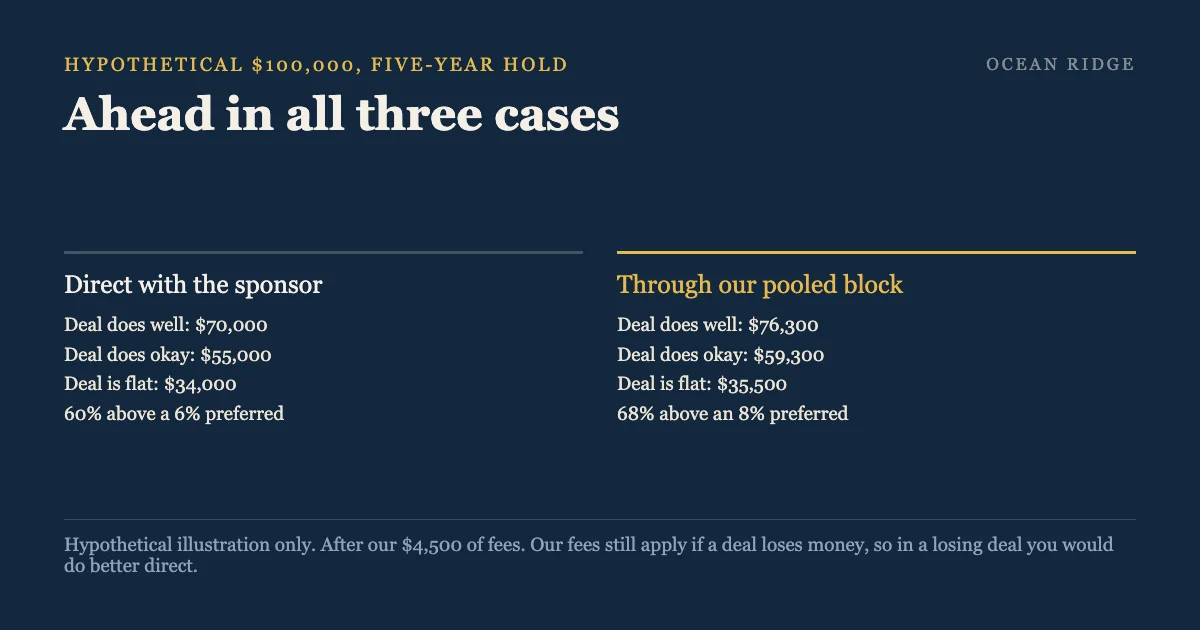
Do I pay more in fees in a fund of funds than going direct?
Not if the vehicle is built right.
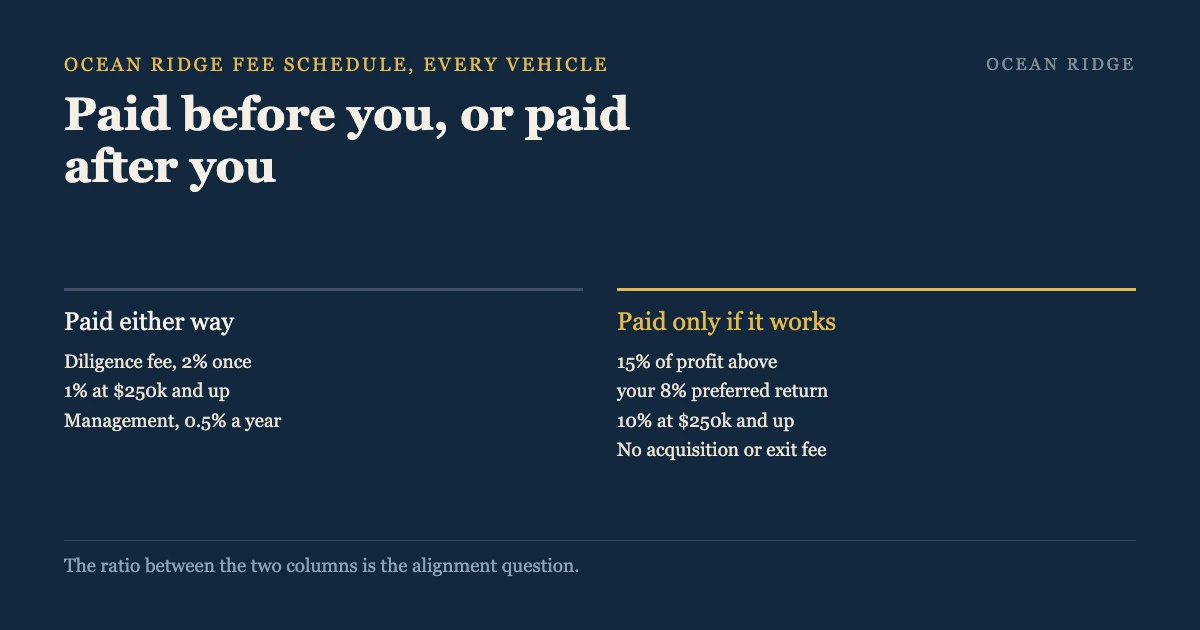
On our most recent equity vehicle, three ways. A one-time diligence fee, a 0.5% annual management fee, and a share of profit we only earn after you receive your 8% preferred return. No acquisition, disposition, financing or construction fees. Our income products, planned for 2027, are paid differently, and their terms will be in their own offering documents.
For educational purposes only. Nothing on this page is investment, legal or tax advice, and nothing here is an offer to buy or sell any security. Ocean Ridge Capital Partners, LLC is not a registered investment adviser, broker-dealer, law firm or accounting firm.
You want to know if our incentives match yours. The useful version of that question is not how much a manager earns, but when. Fees paid no matter what keep the lights on. Money that only shows up when you do well is what lines a manager up with you. Every fee schedule tells you how much of each a manager has built in.
| Fee | When it is paid | Under $250k | $250k and up |
|---|---|---|---|
| Diligence fee | Once, when you invest, on top of your investment | 2% | 1% |
| Management fee | Every year | 0.5% | 0.5% |
| Our share of profit above your 8% preferred return | Only after you receive your preferred return | 15% | 10% |
These are the terms on our most recent equity vehicle. Each vehicle sets its terms in its own offering documents. The sponsor below us charges its own fees, and we send you that full schedule before you commit.
Two of these get paid whether or not the deal works, the diligence fee and the management fee. On $100,000 over five years, that is $4,500. The profit share is the only part tied to results, and it sits last in line. We earn nothing above our fees until you have your capital back plus your full 8% preferred return.
This works on any manager, including us.
Differently. An income fund usually has no profit share. The manager is paid from the difference between what the underlying fund pays and what investors receive. That makes the test simpler. Do you net at least what you would get going direct? For every vehicle we offer, income or real estate, the answer has to be yes in our underwriting, after our fees, or we do not offer it.
On our most recent vehicle, Ocean Ridge’s own money went into the same class as investors, on the same terms. A loss reaches us in the same order it reaches you. When you ask any manager about co-investing, ask three things. Is it the same class as yours? Is it real cash, or a waived fee counted as cash? And does it stand in the same place in line?
Every manager has costs, and fixed fees are not a red flag by themselves. What matters is the mix. We keep the fixed part small and put our upside behind your preferred return, so we do well when you do well.
We also hand you both fee schedules, ours and the sponsor’s, because the total of the two is what you actually pay. A manager who charges nothing at one layer and plenty at the other has not saved you anything.
If the deal underneath is weak, a clean fee table will not save it. Judge the asset and the sponsor first. And do not compare an equity fee schedule to a credit fund line by line. A 0.5% fee over a seven-year equity hold and a spread on a two-year loan book are different things. Compare what you net.
Yes. It is charged either way. The profit share is the part that depends on results.
Only after you have received your capital back plus your full 8% preferred return.
Sometimes, usually in the layer below. Ask for both fee schedules and add them together.
Yes, in full. If a sponsor will not share its complete fee schedule, that tells you something.
If you are weighing a deal this year, book an investor strategy call.
Published · Last reviewed
Next step
Not ready to talk? Take the investor quiz and we will send what fits.
Keep reading
How we investBuilding net worth
Not if the vehicle is built right.
How we investBuilding net worth
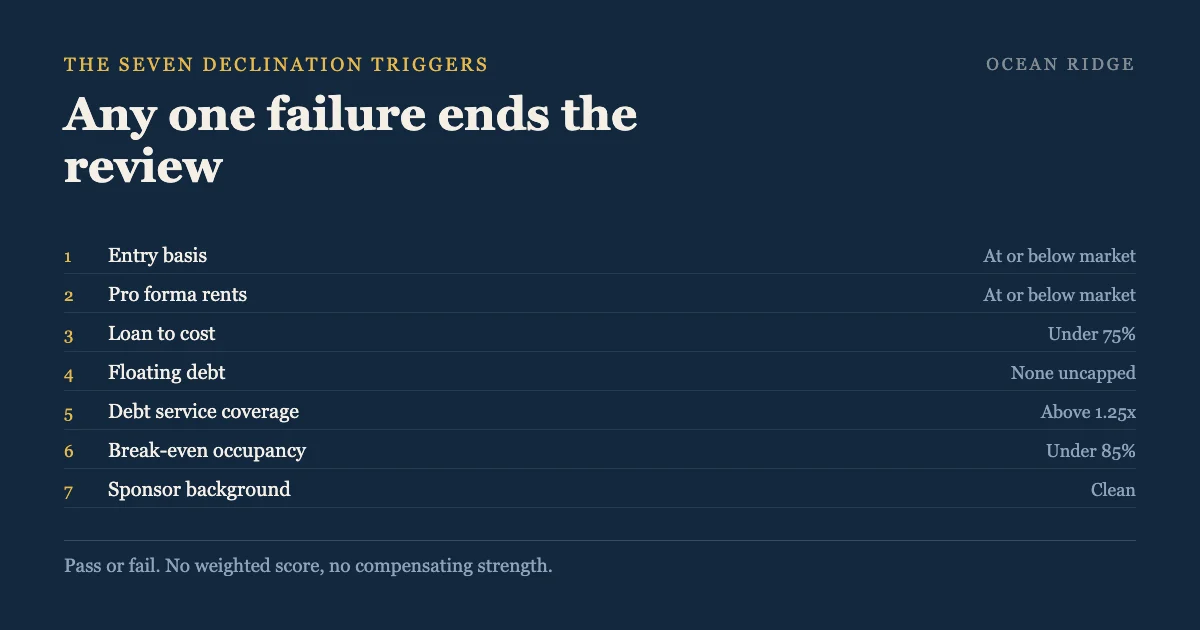
Declination triggers are seven pass/fail tests we run on every real estate equity deal before we spend a day on diligence.